COMMUNITY ASSOCIATION COVERAGE
HOA Insurance
Comprehensive coverage solutions designed to protect your community association, its board members, and the residents you serve. From property and liability to D&O and fidelity bonds, we've got your community covered.
COVERAGE OPTIONS
Complete HOA Insurance Protection
Property Coverage
Master policy protection for common areas, structures, and shared amenities
General Liability
Bodily injury and property damage protection for common areas and amenities
Workers Compensation
Coverage for employees and volunteers injured during association duties
Umbrella / Excess Liability
Extra layer of protection across all liability coverage forms
PROPERTY COVERAGE
Master Property Insurance
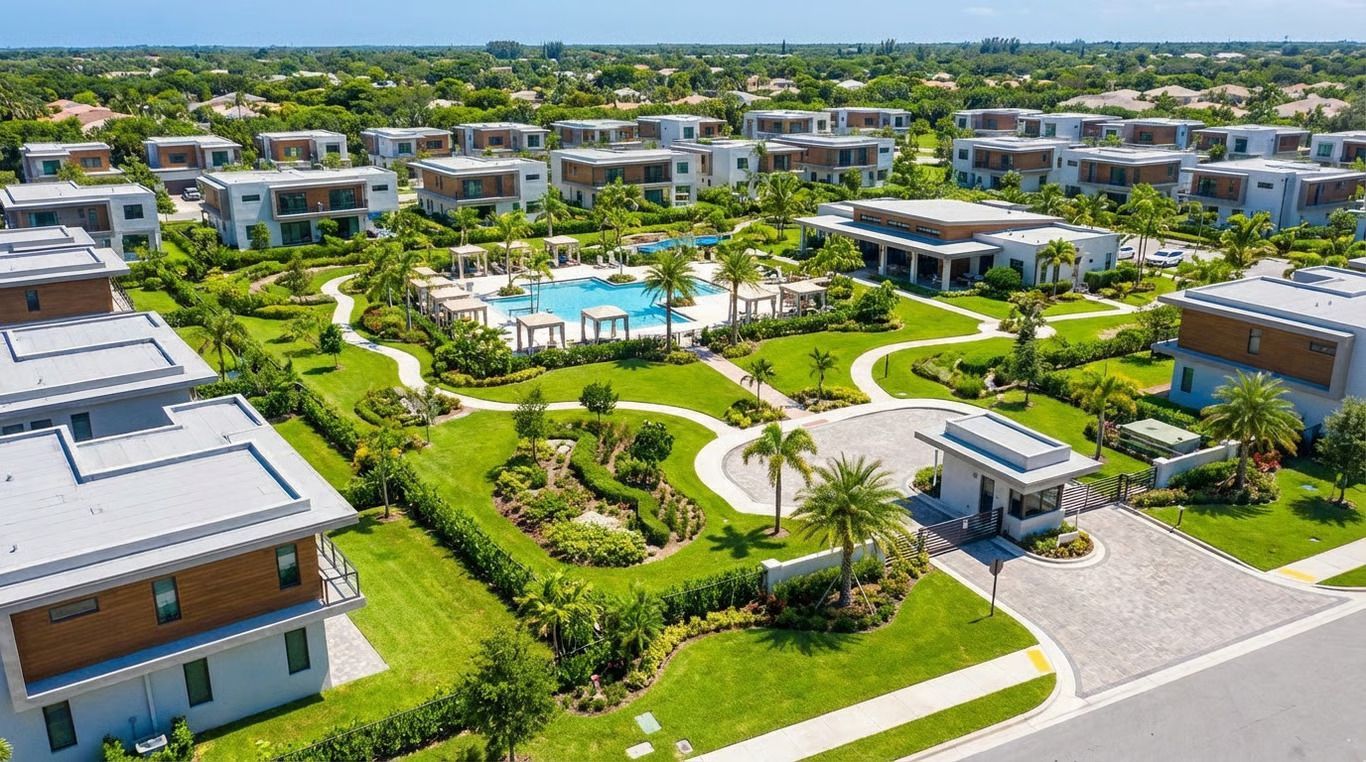
One of the most critical aspects of your community's master insurance program is property coverage. This protects your association's shared structures, common areas, and amenities from damage caused by fire, storms, vandalism, and other covered perils.
Your master property policy typically covers building exteriors, clubhouses, pools, fitness centers, landscaping, and other common-area improvements. We'll help you determine the right coverage limits based on your community's replacement cost, ensuring you're fully protected without overpaying.
GENERAL LIABILITY
Commercial General Liability
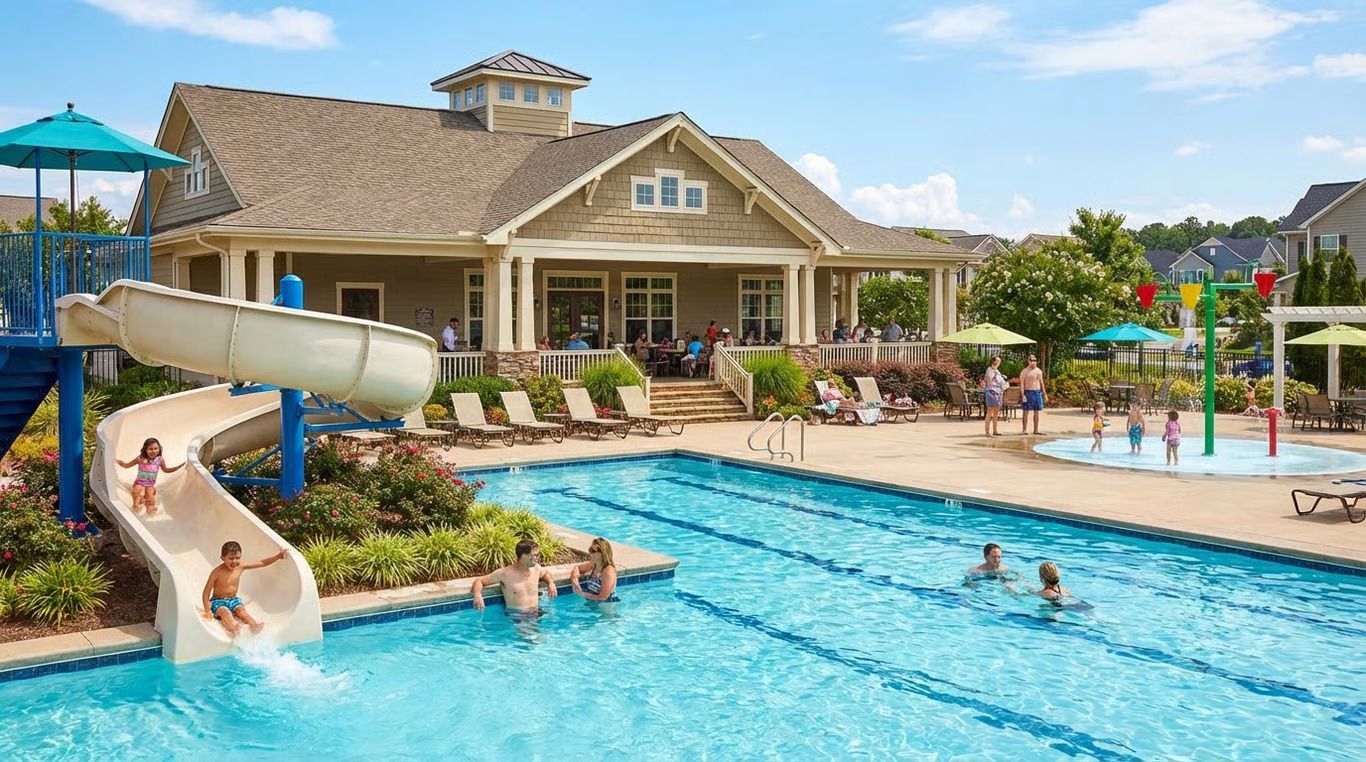
Commercial General Liability (CGL) is one of the most crucial aspects of insurance your community association will carry. It protects against claims of bodily injury and property damage occurring in common areas, amenities, and association-managed spaces.
Whether a visitor slips on a wet pool deck, a child is injured on playground equipment, or property damage occurs during common-area maintenance, your CGL policy responds. We ensure your limits are adequate for your community's exposure and that no gaps exist between your property and liability coverage.
DIRECTORS & OFFICERS
D&O Liability Protection
Your board members and volunteers make important decisions every day on behalf of the community. Directors & Officers (D&O) insurance protects these individuals from being held personally liable for decisions made in good faith for the association.
From enforcement of CC&Rs to budget decisions and vendor selection, board members face potential lawsuits from disgruntled homeowners. D&O coverage provides defense costs and protects personal assets, making it essential for attracting and retaining quality board volunteers.
FIDELITY & CRIME
Fidelity Bond Coverage
A fidelity bond protects your HOA's financial assets against embezzlement and theft by officers, directors, employees, management companies, and anyone involved in administering the association's funds.
Many CC&Rs and state laws require this coverage, and for good reason, community associations manage significant reserve funds and monthly assessments. We'll ensure your bond limits meet both legal requirements and practical needs based on your association's financial exposure.
WHY RIVERSTONE
HOA Insurance Expertise You Can Trust
Community association insurance requires specialized knowledge. We understand the unique risks boards face and build programs that protect your community, your volunteers, and your residents.
HOA Insurance Specialists
We specialize in community association insurance, from condominiums and townhomes to planned communities and mixed-use developments.
Claims Advocacy
When claims arise, our team advocates on your behalf to ensure fair and timely resolution. We guide you through every step of the process.
Annual Policy Reviews
We conduct yearly policy reviews to ensure your coverage keeps pace with property values, new amenities, and changes to your community.
FAQ
Common HOA Insurance Questions
What does an HOA master policy typically cover?
A master policy generally covers building exteriors, common areas, shared amenities like pools and clubhouses, and liability for accidents in those spaces. Individual unit interiors are typically the homeowner's responsibility under their own HO-6 policy.
Is D&O insurance required for our HOA board?
While not always legally required, D&O insurance is strongly recommended. Board members can be held personally liable for decisions affecting the community, from CC&R enforcement to budget allocation. Most well-managed associations carry this coverage to attract and retain quality volunteers.
What is a fidelity bond and why do we need one?
A fidelity bond protects your HOA's finances from theft or dishonesty by anyone who handles the association's money, including board members, management companies, and employees. Many CC&Rs and state laws require this coverage, and bond limits should reflect your association's total financial exposure.
Does our HOA need earthquake or flood insurance?
Standard property policies typically exclude earthquake and flood damage. These require separate policies and are especially important for communities in high-risk zones. We can evaluate your community's exposure and help you determine if these additional coverages are needed.
What is umbrella/excess liability coverage?
An umbrella policy provides an extra layer of protection that sits above your general liability, D&O, and other liability policies. When a claim exceeds the limits of your underlying coverage, the umbrella policy kicks in, providing critical additional protection for your community.
How often should we review our HOA insurance?
We recommend an annual policy review to ensure your coverage keeps pace with property values, new amenities, community growth, and any changes to state laws or CC&R requirements. We conduct yearly reviews with all of our HOA clients to identify any coverage gaps.
READY TO GET STARTED?
Protect Your Community Today
Get a comprehensive HOA insurance review. We'll identify coverage gaps and find competitive rates for your community.